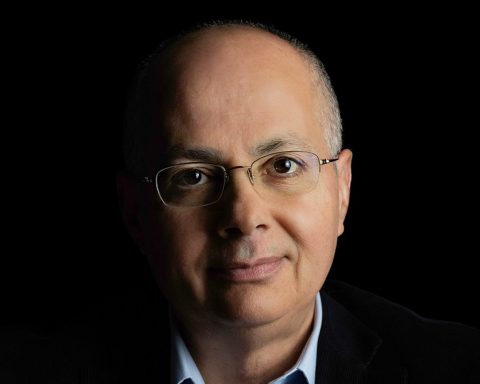
Anne Boden spent more than three decades working inside major financial institutions before deciding that the banking industry needed a different approach. In 2014, at an age when many professionals might have been considering the final stage of their careers, she founded Starling Bank to rethink how people manage their money. Building a bank from scratch would require capital, regulatory approval, and years of persistence – but Boden believed her experience had shown her what traditional banking was missing.
Her journey is about more than launching a digital bank. It is a story of turning industry knowledge into an entrepreneurial opportunity, rebuilding after a serious early setback, and challenging assumptions about who gets to lead a technology company.
Key Takeaways
- Anne Boden used more than 30 years of experience in banking and technology to identify opportunities for a new kind of digital bank.
- She founded Starling Bank in 2014, building its services from scratch rather than simply modernizing an existing bank’s systems.
- After repeated investor rejections and the departure of an early leadership team, Boden rebuilt the business and secured major investment.
- Starling’s growth demonstrated that a digital-first bank could compete by combining modern technology with customer-focused services.
- After leaving Starling’s leadership and later selling her remaining shares, Boden turned her attention toward a new venture focused on artificial intelligence.
From Swansea to the World of Banking
Anne Elizabeth Boden was born in January 1960 and grew up in Bon-y-maen, an area of Swansea, Wales. Her father worked for British Steel, while her mother worked in a department store. Boden has described her upbringing as an ordinary working-class background, with parents who encouraged her curiosity and supported her education.
She developed an early interest in science, technology, and understanding how things worked. That interest led her to Swansea University, where she studied computer science and chemistry, graduating in 1981. The combination would prove useful in a career that increasingly depended on the relationship between financial services and technology.
Boden joined Lloyds Bank as a graduate trainee rather than pursuing a conventional scientific career. Her decision placed her at the intersection of banking operations and emerging computer systems at a time when financial institutions were becoming increasingly dependent on technology.
The early choice helped establish the direction of her career. Instead of treating banking and computing as separate disciplines, Boden developed an understanding of how technology could shape the way financial services operated. She later earned an MBA from Middlesex University while continuing to work.
Three Decades Inside Traditional Banking
Before becoming an entrepreneur, Boden built a career across several major financial institutions. Her professional experience included roles at Standard Chartered, UBS, Aon, ABN AMRO, Royal Bank of Scotland, and Allied Irish Banks.
These positions exposed her to different parts of the financial industry, from technology systems and international transaction banking to senior operational management. At Royal Bank of Scotland, she held leadership responsibilities in global transaction banking, while at Allied Irish Banks she became chief operating officer in 2012.
The experience gave Boden a detailed view of how large banks function. She understood the importance of regulatory compliance, reliable payment systems, risk management, and customer trust. She also saw how difficult it could be for established organizations to change processes that had developed over decades.
The 2008 global financial crisis reinforced her concerns. In the years that followed, Boden felt that banking was not adapting to technological change as quickly as other industries. Consumers had grown accustomed to managing travel, shopping, and communications online, yet many banking services remained cumbersome and slow.
Her dissatisfaction was not simply about making banking look more modern. She believed technology could change the underlying customer experience, allowing people to open accounts more easily, understand their spending, and manage their finances with greater control.
By the time she became a founder, Boden had spent years studying the industry’s systems and limitations. She was not entering banking as an outsider trying to understand the problem. She was attempting to build a different solution after experiencing those problems from within.
The Decision to Start a Bank From Scratch
Boden founded Starling Bank in 2014, leaving her established career to pursue a difficult idea: creating a fully digital bank designed around customer needs.
Starting a bank was a substantial undertaking. Unlike many technology startups, a bank cannot simply release an application, attract users, and refine its services without regulatory oversight. It must meet strict requirements involving capital, governance, risk, security, and consumer protection.
Boden also faced a funding challenge. Developing the technology and preparing a new institution for regulatory approval required considerable resources before the business could operate as a bank. She spent months pitching the idea to potential investors and encountered repeated rejection.
In interviews, Boden has discussed the difficulty of persuading people that a middle-aged woman from an ordinary Welsh background could establish a bank. Her profile did not fit the startup stereotype that dominated much of the technology investment world at the time.
Nevertheless, she continued pursuing the project. She arranged professional support, assembled a team, and worked to demonstrate that her proposal was grounded in practical banking knowledge rather than an abstract technology concept.
The early effort came with significant personal and financial pressure. Boden has described accumulating substantial financial obligations connected with the work needed to establish Starling. The experience showed how expensive and uncertain it can be to build a regulated business before it begins generating revenue.
A Major Setback Before Starling Took Off
Starling’s early development was not a straightforward progression from idea to launch. One of its most difficult moments came when Tom Blomfield, an early colleague who had joined as chief technology officer, and several members of the initial leadership team left in 2015. Blomfield went on to establish Monzo, another British digital bank.
The departures threatened to derail Starling before it had fully established itself. Losing key people at such an early stage can be particularly damaging for a startup, where a small group often holds much of the technical knowledge, relationships, and institutional memory.
For Boden, the setback meant rebuilding the team while continuing to pursue investment and regulatory approval. Rather than abandoning the project, she brought in new people and kept the focus on creating the bank she had envisioned.
A turning point came when investor Harald McPike backed the business with substantial funding. That support gave Starling the resources to move forward with the technology, staffing, and regulatory work required to launch.
The company received its UK banking license in July 2016. In May 2017, it launched its first personal current account through a mobile app.
The milestone represented more than a product launch. It meant Starling had progressed through a demanding process involving funding, technology development, hiring, and regulatory scrutiny. Boden’s ability to keep the project moving after its early leadership crisis became an important part of the company’s founding story.
Building a Bank Around the Customer
Starling’s central proposition was straightforward: customers should be able to manage their money through modern technology without being forced to navigate the delays and complexity associated with traditional banking.
The bank developed features that made everyday financial tasks more accessible. Customers could receive instant spending notifications, review spending insights, lock a misplaced card, and manage accounts through their phones. Its mobile-first approach also reduced dependence on physical branches.
These features were not entirely unique in isolation. The broader opportunity was to combine them within a bank designed from the beginning around digital operations. Instead of adding an app to an established infrastructure, Starling could build its systems with the mobile customer experience as a central consideration.
Starling also expanded into business banking, offering accounts and services to small businesses that needed convenient ways to manage payments and cash flow. For many small firms, banking is an operational necessity rather than a product they want to spend time managing. A well-designed digital service can reduce administrative friction and make financial information easier to access.
The company later developed Engine by Starling, a software business that licenses its banking technology to other financial institutions. This opened a route beyond serving its own account holders: Starling’s technology could also support banks seeking to build or modernize digital services.
The strategy illustrates how a company’s internal capabilities can become a separate business opportunity. Technology initially developed to support Starling’s own customers could also be packaged for use by other financial institutions.
From Startup to Established Digital Bank
Starling grew from a small fintech startup into a major UK digital bank. Its development helped demonstrate that a mobile-first institution could do more than provide a convenient interface: it could build the systems, services, and operational discipline needed to function as a regulated bank.
The company received industry recognition and expanded its personal and business banking services. It also reached profitability, an important milestone in a fintech sector where some businesses prioritized customer acquisition and rapid growth while continuing to report losses.
Profitability matters because financial services companies must support substantial ongoing costs, including technology, customer service, fraud prevention, regulatory compliance, and risk management. Growth alone does not guarantee that a bank has a sustainable business model.
Starling also participated in government-backed lending schemes during the COVID-19 pandemic. These programs brought additional operational responsibilities and scrutiny, reflecting the demands placed on financial institutions during a period of economic disruption.
Boden received an MBE in 2018 for services to financial technology. She also became a prominent advocate for women entrepreneurs, drawing on her own experience of fundraising and leadership in an industry where women have historically been underrepresented.
Starling’s progress did not mean every challenge had disappeared. Digital banks still compete with established institutions and other fintech companies, while balancing customer expectations, operating costs, regulation, and risk. Its story is best understood not as proof that traditional banking has become obsolete, but as an example of how a new institution can compete by rethinking the customer experience and building its technology around that goal.
Stepping Down and Moving Beyond Starling
In June 2023, Boden stepped aside as Starling’s CEO. She remained on the company’s board for a further period, leaving that position in June 2024.
The transition marked the end of her day-to-day leadership of the business she had founded. For entrepreneurs, moving away from a company can be complicated: a founder’s identity is often closely connected to the organization, while the business itself must continue evolving beyond its original leadership.
Boden’s next chapter has focused on artificial intelligence. Through AI By Boden, she has indicated an interest in how technology can be applied to financial services and other areas. The venture represents a continuation of her long-standing interest in using technology to change how businesses operate, although its future direction and commercial outcomes remain to be seen.
In October 2026, reports indicated that Boden had sold her remaining 2.7% stake in Starling in a transaction valuing the bank at approximately £1.7 billion. The shares were reportedly acquired by existing shareholders. The transaction was a significant financial and ownership milestone, but it should be distinguished from the broader performance of the business and from the potential of her newer venture.
Her departure from Starling’s ownership also creates a clearer separation between the bank she built and the work she pursues next. Rather than defining her career solely by a single company, Boden is entering another phase in which she can explore how emerging technology may affect financial services.
Beyond building businesses, Boden has also used writing to share what she has learned about banking, technology, and entrepreneurship. Her book Banking On It: How I Disrupted an Industry and Changed the Way We Manage Our Money Forever (2020) recounts her decision to challenge established banking practices and build Starling Bank. She later published Female Founders’ Playbook: Insights from the Superwomen Who Have Made It (2024), which draws on the experiences of women entrepreneurs to explore the practical challenges of building and growing a business. Her earlier work, The Money Revolution: Easy Ways to Manage Your Finances in a Digital World, focuses on how technology is changing personal finance.
What Entrepreneurs Can Learn From Anne Boden
Boden’s journey offers several lessons for people building businesses, particularly in established or heavily regulated industries.
Industry experience can reveal opportunities outsiders miss. Boden spent decades inside banking before deciding to create a different kind of institution. Her understanding of the industry’s systems and constraints helped her identify where a new approach might make a difference.
A compelling idea still needs a viable operating model. Starling required technology, regulatory approval, capital, experienced staff, and customer trust. The ambition to improve banking had to be supported by the practical work of building and operating a bank.
Persistence matters, but rebuilding matters too. The departure of Starling’s early leadership team could have ended the project. Boden’s response was to assemble a new team, continue fundraising, and keep working toward regulatory approval. Persistence was useful because it was paired with changes in how the business was staffed and supported.
Customer experience can be a strategic differentiator. Starling’s mobile-first services were designed to make everyday banking tasks easier. The broader lesson is to look for recurring frustrations in a market and determine whether a better-designed service can solve them sustainably.
Founders must eventually think beyond themselves. Building a company and leading it indefinitely are different responsibilities. Boden’s departure from the CEO role and later exit from the board and shareholding show how a founder’s relationship with a business can change as it matures.
Her story also challenges the assumption that entrepreneurship belongs primarily to young founders with conventional technology backgrounds. Boden entered startup life after a long corporate career, bringing experience that became central to her business proposition. Her path demonstrates that entrepreneurship can begin when accumulated knowledge leads someone to see an opportunity worth pursuing.
Conclusion
Anne Boden transformed her experience inside traditional banking into the foundation for Starling Bank, a digital-first institution built to make everyday financial services more accessible. Her journey included investor rejection, a major early team departure, demanding regulatory requirements, and the challenge of proving that a new bank could operate sustainably.
Starling’s growth established Boden as a significant figure in fintech, but her entrepreneurial story did not end when she stepped down as CEO. With her subsequent departure from the board and sale of her remaining shares, she has moved into a new chapter focused on artificial intelligence and the next possibilities for technology.
Boden has also extended her influence beyond banking through her books, including Banking On It and Female Founders’ Playbook, sharing lessons on disruption, leadership, and building a business. As she turns her attention to AI By Boden, her next chapter remains in development, with detailed product plans and launch timelines not yet publicly disclosed.
For aspiring founders, Boden’s experience offers a practical lesson: a deep understanding of an industry can be the starting point for meaningful change. The challenge is to turn that insight into a business that earns trust, survives setbacks, and continues to deliver value long after the original idea has been launched.
FAQs
Who is Anne Boden?
Anne Boden is a Welsh technology entrepreneur and the founder and former CEO of Starling Bank, a UK digital bank launched in 2014. Before becoming an entrepreneur, she spent more than 30 years working in financial services and technology roles at major institutions.
Why did Anne Boden found Starling Bank?
Boden believed traditional banking had not kept pace with the changes technology had brought to other industries. She founded Starling to build a bank from scratch around mobile technology, convenient services, and a more customer-focused experience.
How did Anne Boden overcome the early challenges at Starling?
She continued pursuing funding and regulatory approval despite repeated investor rejections and the departure of an early leadership team. Support from investor Harald McPike helped the company secure the resources needed to progress, and Starling received its UK banking license in 2016.
When did Anne Boden leave Starling Bank?
Boden stepped down as CEO in June 2023 and left the company’s board in June 2024. In October 2026, reports indicated that she had sold her remaining stake in the bank, completing her exit as a shareholder.
What is Anne Boden doing now?
Boden is focused on AI By Boden, a venture through which she has expressed interest in applying technology to financial services and other areas. Its long-term direction and commercial impact are still developing, so it is best viewed as the next chapter in her entrepreneurial career rather than a proven successor to Starling.
Sources:
- https://en.wikipedia.org/wiki/Anne_Boden
- https://www.bbc.com/news/uk-wales-43217524
- https://www.efinancialcareers.com/news/starling-bank-s-anne-boden-wants-to-hire-anthropic-engineers
- https://www.cityam.com/starling-founder-anne-boden-offloads-stake-at-slashed-1-7bn-valuation/
- https://www.amazon.com/stores/author/B07SRM1DW4
- https://startuptimes.net/anne-bodens-starling-bank-founder-story-rethinking-banking-for-the-phone